Two Technologies, One Destination: Zero-Emission Commercial Transport
As the automotive industry races toward zero-emission transportation, two technologies have emerged as the leading contenders: battery electric vehicles (BEVs) and hydrogen fuel cell vehicles (FCEVs). In 2025, the debate over which technology will dominate commercial transport is reaching a critical point, with both sides making compelling arguments.
Battery Electric: The Current Leader
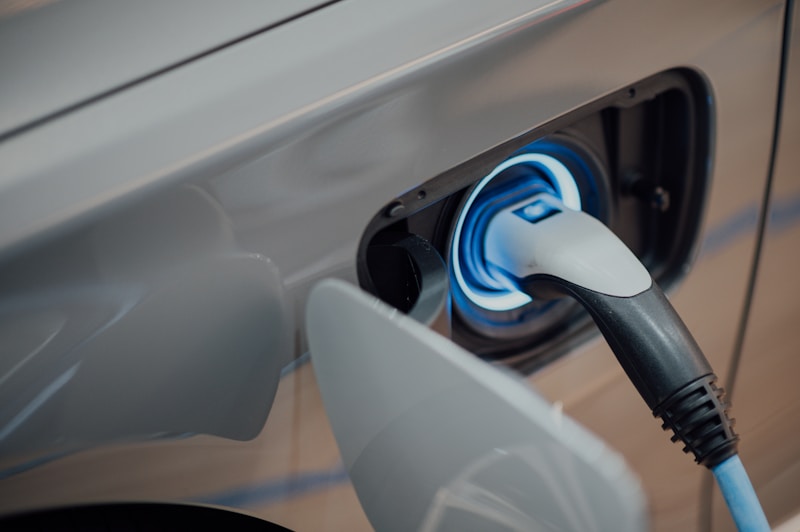
Battery electric vehicles have taken a significant lead in the passenger car market, with global EV sales reaching 20.7 million units in 2025 — a 20% increase from the previous year. The technology's advantages include:
- Proven Technology: BEVs have been in mass production for over a decade
- Well-Developed Infrastructure: Charging networks are expanding rapidly
- Lower Operating Costs: Electricity is cheaper than hydrogen per mile
- High Efficiency: BEVs convert 77-82% of grid energy to wheel motion
Hydrogen Fuel Cells: The Commercial Challenger
While battery electric has dominated passenger vehicles, hydrogen fuel cells are making a strong case for commercial applications, particularly heavy-duty trucking:
- Fast Refueling: Hydrogen tanks can be filled in 10-15 minutes vs. 30+ minutes for large battery packs
- Longer Range: Hydrogen trucks can achieve 500-800 miles on a single tank
- Payload Advantage: Hydrogen tanks are lighter than equivalent battery packs for long-haul applications
- Industrial Synergy: Green hydrogen production can utilize excess renewable energy
Major Hydrogen Initiatives in 2025
Several major automakers are investing heavily in hydrogen fuel cell technology:
- Toyota: Continuing to develop hydrogen fuel cell systems for commercial vehicles, partnering with Kenworth for fuel cell trucks
- Hyundai: Operating hydrogen fuel cell truck fleets in Europe and developing the Xcient Fuel Cell for global markets
- BMW & Renault: Showcasing hydrogen fuel cell concept vehicles at major auto shows
- Nikola: Developing hydrogen fuel cell semi-trucks for the North American market
The Infrastructure Challenge
Both technologies face significant infrastructure challenges. For BEVs, charging infrastructure in rural areas and for long-haul trucking remains limited. For hydrogen, the refueling station network is even more sparse — there are currently fewer than 1,000 hydrogen stations globally, concentrated primarily in California, Germany, Japan, and South Korea.
What This Means for Parts Distributors
Auto parts distributors should prepare for a dual-technology future. While BEVs will dominate passenger vehicles and short-range applications, hydrogen FCEVs will likely capture a significant share of the long-haul trucking, bus, and industrial vehicle markets. Both segments will require specialized components — electric motors and battery systems for BEVs, fuel cell stacks and hydrogen storage systems for FCEVs.
Carval Auto Parts is committed to supporting both technologies as the industry evolves toward zero-emission transportation.